Travel Insurance for Couples and Family Nomads
Last updated: October 22, 2026
Key Takeaways
- Family nomad insurance changes the risk unit for a household.
- The practical test is not “which looks cheaper,” but which policy structure fits how the family travels.
- Check the wording, family definition, and evacuation clause before you pay.
- Get qualified help when family, residency, or medical details make the wording hard to apply.
Travel insurance for couples and family nomads is about matching one policy to shared trips, shared risks, and shared medical limits. It is not just “insurance for two people”; once children, custody, evacuation, and trip dates overlap, the wording can decide whether a claim pays or is rejected.
This is information, not financial advice. Insurance rules, policy wording, residency tests, and medical limits vary by country and change often, so a qualified adviser should review your own situation before you bind coverage.
Who this is for — and who should use something else
This guide is for couples, married or unmarried, and family nomads who move between countries for months at a time and want to understand how one policy can cover more than one traveler. It assumes you already know your route, your likely trip length, and which adults and dependent children will travel together for at least part of the year. It also assumes you are comparing policy structures, not trying to settle a claim.
Family nomad insurance matters most when travelers share the same itinerary but not always the same travel pattern. One adult may take a work trip for 10 days while the other stays put with a child; a dependent child may fly home earlier than the parents; or everyone may need a joint policy that treats the household as one insured unit. Those differences can affect eligibility, coverage dates, and the way medical maximums apply, so check the policy wording carefully and, if needed, consult a qualified adviser. For background, see the nomad travel insurance plan types guide.
This page is not for someone who wants the “best” plan ranked against every competitor, and it does not try to answer one-way-ticket or multi-country-routing questions. It is also not the right tool if you want travel insurance for a single short leisure trip under 30 days, or if one traveler needs a specialist policy because of a serious pre-existing condition that the insurer will not accept on standard terms. In those cases, the policy structure changes enough that generic family guidance stops being useful.
The key question here is simple: do you need one joint policy, or separate policies that happen to be bought together? That choice can affect medical coverage for the adults, child cover, baggage treatment, evacuation rules, and what happens if one family member changes plans. Check the wording and, if the structure is unclear, consult a qualified adviser. See also our travel insurance for couples page for a narrower comparison.
What family nomad insurance actually changes
Family nomad insurance changes the risk unit. A couple can usually be underwritten as two named adults on one contract, but a family nomad policy adds dependent child coverage and sometimes different rules for ages, school terms, and travel accompaniment. The insurer may define a dependent child by age, financial dependence, and whether the child travels with an insured adult. That definition is not universal; it can differ by insurer and by country of issue.
The biggest change is the medical limit. A policy may advertise a single overall medical maximum for the whole family, or it may apply the limit per person. Those are not the same thing. If the policy uses one shared pot, one adult’s hospital claim can reduce what remains for everyone else. If the limit is per person, the family has more separation, but the premium structure and underwriting rules can be stricter.
A second change is medical evacuation. Evacuation means transport to a facility that can provide the care the policy says is medically necessary, not a private flight home because the schedule is inconvenient. For families, the policy has to say what happens if one child is evacuated alone, if one parent accompanies the child, or if an adult must stay behind to care for another minor. That wording matters far more than a glossy “worldwide emergency” label.
The third change is administrative. Family policies often require all named travelers to live at the same address, share the same primary trip dates, and be listed on the policy from the start. If the family splits up for part of the year, the insurer may treat that as a trip variation, not a minor schedule update. A generic couple policy can be more forgiving because there are only two adults; once dependent children enter the picture, the rules get narrower. If you are unsure, ask the insurer or a broker to confirm the trip pattern in writing. The family travel insurance page explains the broader setup.
If the household is stretched across multiple passports, school calendars, or custody arrangements, the policy wording deserves as much attention as the price. The hub on nomad travel insurance plan types is the right place to compare structures, but this page is about how the family version changes the mechanics.
How do you choose between a joint policy and separate policies?
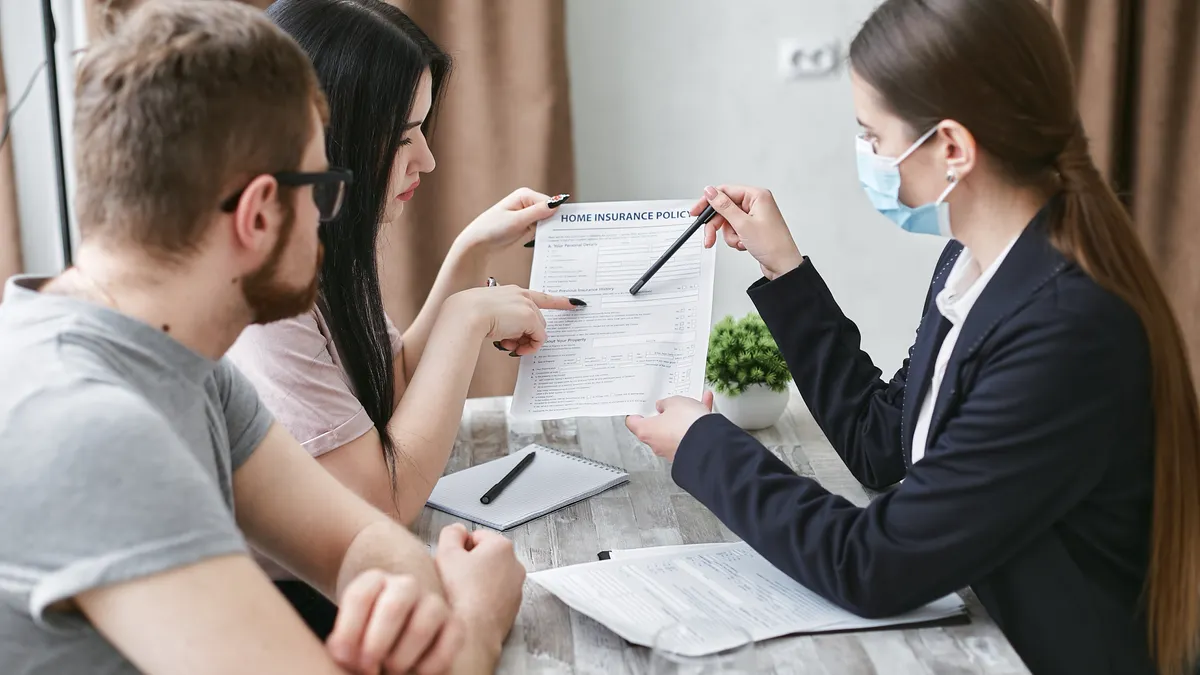
A joint policy works when the adults and any dependent child can all be insured under one contract with one common trip structure, while separate policies work when one traveler’s needs would distort the others’ coverage. The practical test is not “which looks cheaper,” but “which policy structure matches the way the family actually travels.”
Start with the insurer’s definitions. Look for the section that defines spouse, partner, dependent child, and family. If the policy says children must travel with an insured adult, verify whether “with” means on the same itinerary, in the same country, or simply under the same umbrella policy. A family may look eligible on the surface and still fail the definition if one child is 19, studying away from home, or traveling independently for two weeks.
Then compare medical limits. A joint policy often gives one shared family limit, which can be enough for routine emergencies but thin if one traveler ends up with a serious admission. Separate policies can isolate claims, but they can also create gaps if one adult’s policy excludes accompanying minors or if a child’s policy does not include the same evacuation terms as the parents’.
The way to proceed is methodical:
- List every traveler by name, age, citizenship or residency status, and usual country of residence. Verify that each person meets the insurer’s eligibility rules. A problem is any traveler who does not clearly fit the definition of spouse, partner, or dependent child.
- Write down the exact travel pattern for the next 12 months, including country changes, school breaks, and any period when one adult travels alone. Verify the policy accepts that pattern as one continuous trip or a series of trips. A problem is a policy that requires all insured people to travel together at all times.
- Check whether the medical limit is per person or per policy. Verify the limit applies in the countries you plan to enter, not just “worldwide” in marketing language. A problem is a shared family limit so low that one hospitalization could exhaust it.
- Review how pre-existing conditions are handled for each insured person. Verify whether the same medical screening applies to adults and children. A problem is one family member needing an exclusion or medical rider that the others do not need.
- Read the evacuation clause line by line. Verify whether a dependent child can be evacuated with one parent, both parents, or an appointed escort. A problem is wording that covers evacuation only for the patient, not for the caregiver who must travel with the child.
- Check trip interruption and return-home wording. Verify what happens if one adult is hospitalized while the other must care for children or return to work. A problem is a benefit that pays only for the injured traveler and ignores the household disruption.
- Confirm age limits for dependent children and any schooling or financial-dependence tests. Verify the policy’s age cutoff in writing, because 18, 19, 21, and 24 are all used in different contracts. A problem is assuming a child remains covered after the policy’s cutoff age.
- Ask whether the insurer requires all insured people to share one policy start date and one end date. Verify how partial extensions are handled. A problem is one traveler needing an extension while the rest of the family cannot be extended on the same terms.
The right structure is usually the one that best matches the strictest traveler, not the cheapest adult-only quote. That is especially true when a dependent child is involved, because the child’s evacuation and accompaniment rights can be narrower than the adults’ rights even on a family plan. The wrong structure is one that saves money by weakening the exact clause you are most likely to need. For a deeper checklist, see our travel insurance checklist.
What should you check before you bind coverage?
You should check the policy wording, the family definition, and the medical evacuation clause before you pay anything. That sounds basic, but the family version of travel insurance can hide its most important restrictions in the certificate, not the sales page.
First, verify who is actually insured. A couple policy may define the insured adults clearly but treat children as automatic dependents only if they are named on the schedule. If a child is not listed, they may not be covered at all, even if the policy marketing uses family language. Check the names, dates of birth, and passport details for every traveler.
Second, check whether the policy uses one medical limit for the whole family or separate limits. If the wording says “per policy period” or “aggregate,” that is a shared pool. If it says “per insured person,” each traveler may have their own cap. That distinction matters in a hospital stay lasting several days or longer, especially in countries where private treatment is expensive.
Third, verify evacuation for minors. Family nomads often assume a child will be flown with a parent, but the contract may only promise transport for the patient. Read for terms such as “escort,” “accompanying adult,” “family reunion,” and “repatriation.” Repatriation means return to the home country or place of residence, which is not the same as local medical transfer. If the child needs an escort and the policy is silent, that silence can become a claim dispute.
Fourth, confirm the policy’s treatment of separation. A family may spend part of the year apart because one adult is working remotely in another country or one child is staying with relatives. Some policies require the insured family unit to travel together on the same itinerary; others do not. If the wording does not clearly allow split travel, assume it does not.
Fifth, check the purchase timing. Some policies require you to buy before departure from your home country, before a trip starts, or before your current policy expires. If you are already traveling, late purchase rules may be narrower. A quote that looks acceptable can become unusable if the start date, residence declaration, or prior-trip history is wrong.
For a reliable framework, the U.S. Centers for Disease Control and Prevention’s travel health guidance and the European Insurance and Occupational Pensions Authority’s consumer information on insurance are useful reference points for understanding what travel insurance does and does not do, though neither replaces policy wording. For more official guidance, see the CDC Travelers’ Health site and EIOPA consumer information.
When should you stop and get qualified help?
You should stop and get qualified help when the family structure, residency, or medical profile makes the policy wording hard to apply cleanly. This is not the place to guess, because the cost of a mismatch is usually a denied claim or an unexpected uncovered evacuation.
One traveler has a serious pre-existing condition: The family may need a medical screening, exclusion, or specialist policy wording — get a broker or adviser to review the medical disclosure before buying. A hidden exclusion can be more expensive than a slightly higher premium.
A dependent child will travel without both parents: The policy may not cover escort, consent, or guardianship issues — confirm the child’s evacuation and accompaniment terms in writing before departure.
The adults live in different countries or use different tax residencies: The insurer may not treat the household as one family unit — ask for written confirmation of eligibility, because residency mistakes can invalidate the contract.
One parent may extend the trip while the other returns home: The shared policy may not allow asymmetric dates — get the extension rules in advance, or separate the policies if the contract cannot accommodate the split.
The household is blended, split-custody, or includes stepchildren: The legal relationship may not match the insurer’s dependent-child definition — verify custody and dependency requirements, because a family label alone is not enough.
You need evacuation across borders for a child with a guardian who is not the insured parent: The policy may not cover the substitute escort — speak to the insurer or a qualified adviser, because this is a documentation issue as much as an insurance issue.
If any of those situations apply, the standard couple-and-family guidance stops being precise enough. A qualified adviser can read the wording against your actual travel pattern, which is better than assuming a family policy will bend to fit the trip.
The mistakes couples and family nomads make most often
The most common mistake is treating “family” as a marketing term instead of a contract term. A policy can say family and still exclude a 20-year-old dependent, a child traveling part-time, or a spouse who does not meet residency requirements. The consequence is simple: the claim can be denied because the traveler was never eligible. The correct alternative is to check the definition page, not the brochure.
A second mistake is assuming a joint policy is always better than separate policies. A shared policy can be simpler, but it can also pool the medical limit and link every traveler to the same exclusions. If one person needs a rider or a higher limit, the whole policy may become more expensive or less flexible. The better alternative is to compare the structure, not just the price.
A third mistake is ignoring evacuation wording for minors. Parents often read “medical evacuation” and stop there, but a child’s case can require an accompanying adult, a translator, or a transfer to a pediatric facility. If the policy does not address escort costs, the family may face separate out-of-pocket charges. The better alternative is to read the evacuation section and the assistance line in full.
A fourth mistake is leaving a child off the certificate because the traveler is “obviously included.” On a family nomad policy, obvious is not enough. If the dependent child is not scheduled, named, or otherwise attached to the policy, the insurer may treat the child as uninsured. The correct alternative is to verify every name and date of birth before payment.
A fifth mistake is buying a policy that fits the current month but not the next 6 months. Family nomads often move in stages, and the policy needs to survive changes in school calendars, visas, and lodging plans. The consequence is administrative friction at renewal or extension time. The correct alternative is to check whether the insurer allows mid-term updates and how those changes affect the premium and coverage dates.
What does a good family policy look like in practice?
A good family policy is one that matches the household’s actual travel pattern, clearly names every insured person, and spells out how dependents and evacuation are handled.
Drafted with AI; not yet reviewed by a person.